
The U.S. Energy Information Administration (EIA) published its Monthly Energy Review report on August 29th, 2026, and its Monthly Biofuels Capacity and Feed Stocks Update Report on August 30th, 2026. In this article, we will conduct a descriptive analysis of pure biodiesel (B100) production and its feedstocks usage.
Biodiesel Production and Five-Year Average
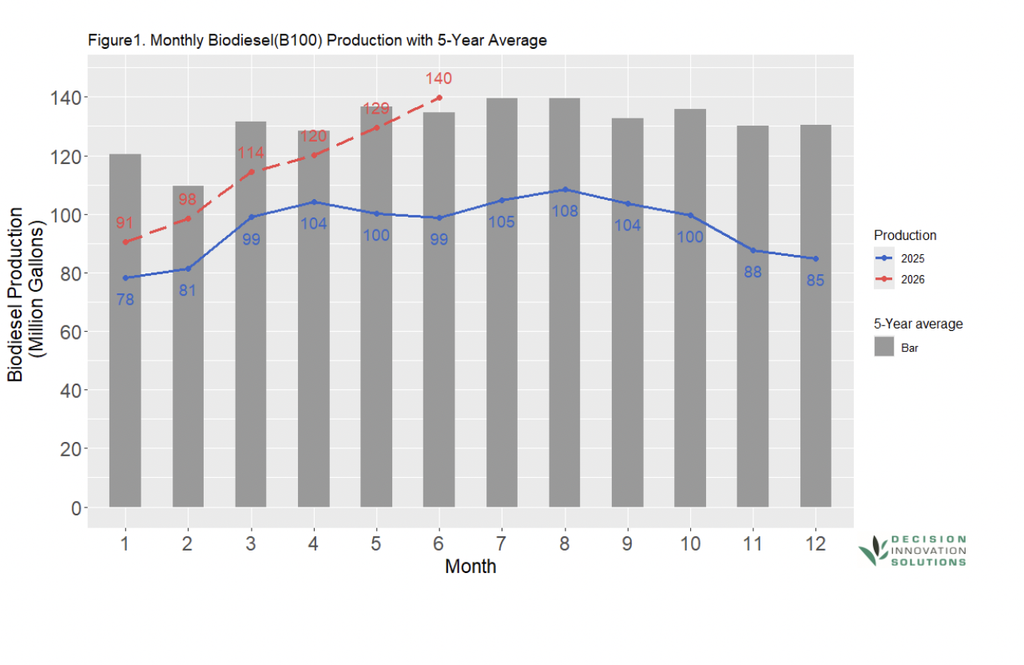
EIA reported an average of 115.5 million gallons of pure biodiesel was produced in January through June 2026, which was 26 million gallons more when compared to the average of the first half year of 2025, and more than 132 million gallons more compared to the total production in the same time period. In Figure 1, the red dashed line represents B100 production in 2026. The blue solid line represents B100 production in 2025. The gray bar represents the 5-year average (2021 to 2025) biodiesel production for each month. Biodiesel production in all 12 months of 2025 was about 25% lower than the 5-year average, while the biodiesel production in the first six months in 2026 comes back to the 5-year average level gradually, which is due to clean fuel production tax credits and the extension of Section 45Z1, according to IRS.
Biodiesel Feedstocks Usage Five-Year Outlook
Figure 2 shows the monthly usage of vegetable oils, i.e., canola oil (represented by red color), corn oil (green color) and soybean oil (blue color), in biodiesel production from January 2021 to June 2026. Some data records for canola oil are missing because EIA withheld them to avoid disclosure of individual company data. Soybean oil remains the largest oil input for the entire study period, except for the first two months in 2025, which was replaced by tallow for those two months.
For the six months in 2026, soybean oil inputs to biodiesel production were 7,533 million pounds (34.7% of total feedstock input so far in 2026), 2,571 million pounds soybean oil input more than the same time period in 2025. Canola oil input was 1,759 million pounds to biodiesel production (9.5% of total feedstock input in 2026), 724 million pounds canola oil input less than the same time period in 2025. Corn oil input was 2,385 million pounds (12.9% of total feedstock input in 2025), 192 million pounds corn oil input more than the same time period in 2025.
Application of simple linear regression models on vegetable oil inputs across time results in significantly increasing trends for all three vegetable oil inputs over time, shown in Figure 2. For the last five years though, soybean oil is the top feedstock contributor for B100 production even though the percentage of soybean oil input has decreased among all oil inputs, from its high point in 2020 of 65.9% to 46.0% in 2022, 35.0% in 2024, and 33.2% in 2025. However, the percentage of soybean oil input increased in the first half year of 2026, back to 41.2%, primarily driven by sweeping structural shifts in U.S. federal biofuel policies 2.
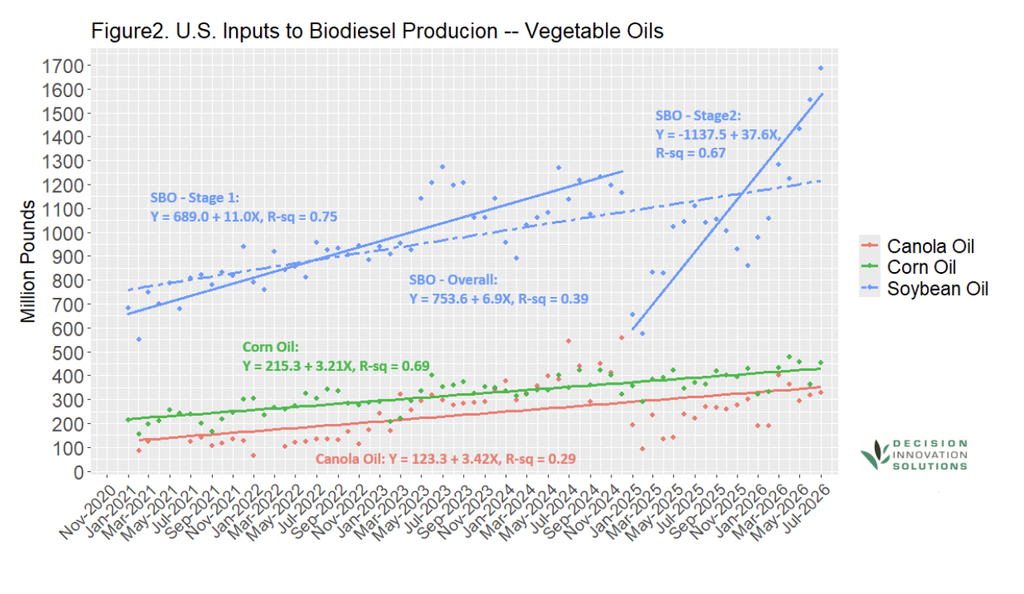
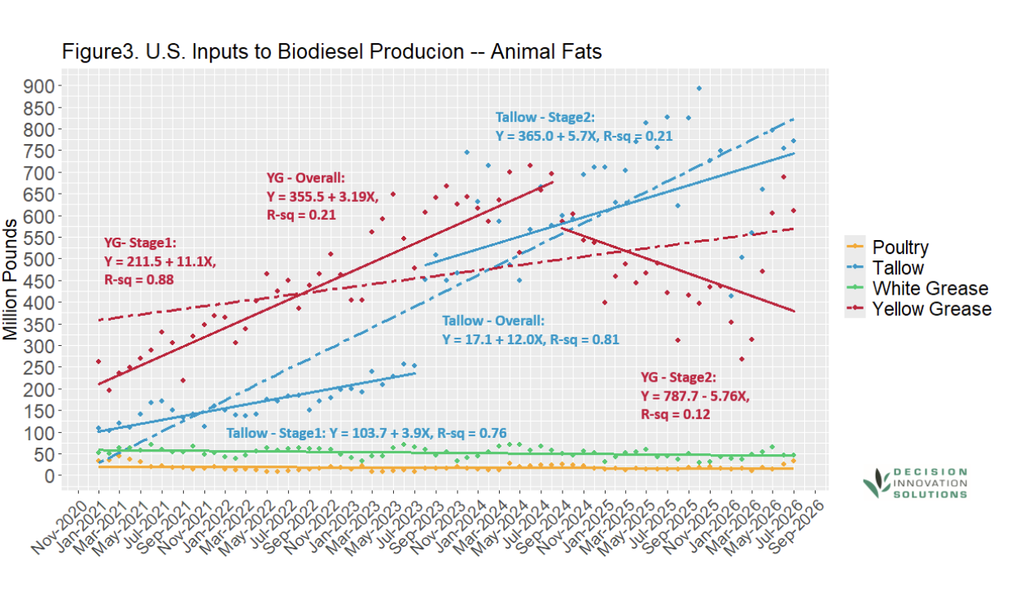
Figure 3 shows the monthly usage of virgin and recycled vegetable oils and animal fats, i.e., poultry fat (represented by yellow color), tallow (blue color), white grease (green color, also called choice white grease) and yellow grease (red color), in biodiesel production within the same study period. Again, some data records for poultry fat and tallow are missing because EIA withheld them to avoid disclosure of individual company data.
Yellow grease, which includes recycled cooking oil, was the top animal fats and recycled feedstock input to U.S. biodiesel production before 2025. However, after 2025, it became the second largest animal fats and recycled feedstock input, and kept dropping down, until early 2026. The decreasing trend was due to a policy3 that any yellow grease sources outside the U.S., Canada or Mexico is banned from inclusion in biodiesel production. In the first six months of 2026, yellow grease usage was 2,700 million pounds, 49 million pounds less when compared to the same time period in 2025, which remained the same level in both first half year of 2025 and 2026. Then an increasing trend has been seen over the last four months, this may be because the domestic supply chains have successfully normalized.
For the studied period, tallow input, with 3,685 million pounds, decreased 15.9% compared to the same time period in 2025, with 4,383 million pounds, and increased 7.3% more compared to tallow inputs in 2024. After the year 2025, tallow became the dominant animal fats and recycled feedstock input. Notice that for January and February in 2025, tallow input was 710.3 million pounds and 630.3 million pounds, respectively, and it was the top input among all vegetable oils and animal fats and recycled feedstock inputs, which was even higher than soybean oil, which has been the top input of biodiesel production for more than a decade.
Poultry fat input increased 16.4% from 85.8 million pounds to 99.9 million pounds between the first six months in 2026 to the same time period in 2025. White grease input remained at the same level in the first six months in 2025 and 2026, with 286 million pounds.
Animal fats and recycled feedstock usage captured about 36.7% of total feedstock usage in the studied period in 2026. Tallow accounted for 20.0% of that 36.7%, following by yellow grease with 14.6%, white grease with 1.6%, poultry fat with 0.5%, and with “other” input unknown. The animal fats and recycled feedstock usage decreased about 23.2% compared to the first six months in 2025.
Tallow input has shown increasing trends in biodiesel production, in general. Tallow and yellow grease became the number two and number three fats & oils inputs for biodiesel production, respectively, since 2025. Regression models indicate the same conclusion, tallow input (for both overall period and two stages, stage1: January 2021 to July 2023, and stage2: August 2023 to June 2026), and yellow grease input has a significant increasing trend until August 2024 (YG stage 1), then a decreasing trend has been seen since September 2024 (YG stage 2), shown as the blue equation and red equation, respectively, in Figure 3.
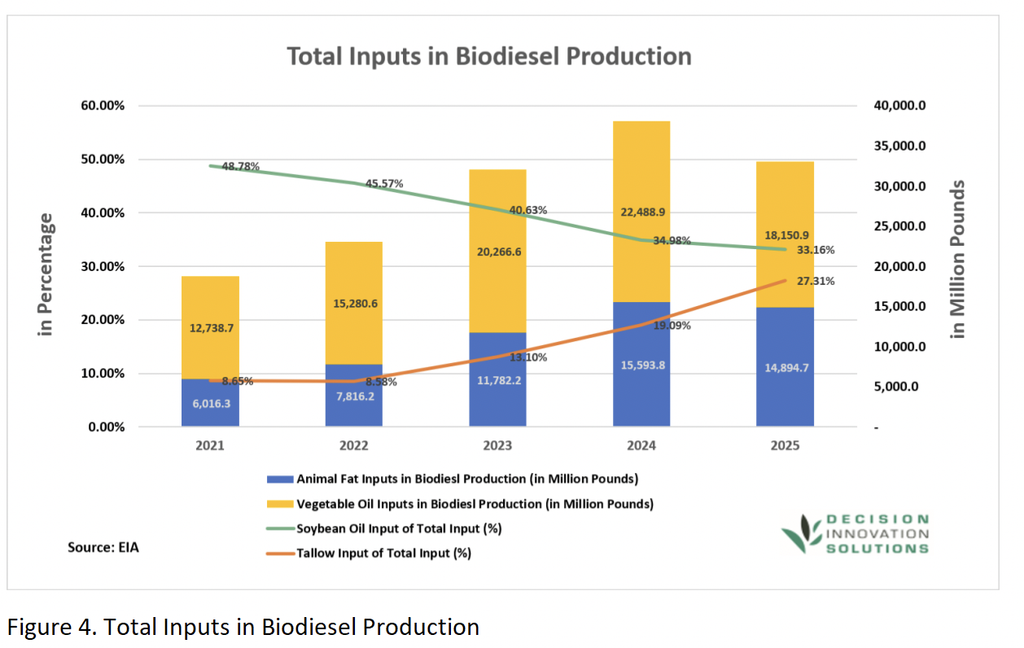
Since 2026 is not yet complete, in Figure 4, data only compared from 2021 to 2025. Animal fats input has seen a significantly increasing trend from 2021 to 2025, from 32.1% of total input to 45.1%. It dropped to 36.8% of the total input in the first six months of 2026. Among the four animal fats, tallow input increased from 8.7% of the total input to 27.3% in 2025 and dropped to 20.0% of the total input in the first six months in 2026. On the other hand, soybean oil input was 48.8% of the total input in 2021, it dropped down to 33.2% in 2025 and went back to 40.8% of the total input in the first six months in 2026. The input share of soybean oil is declining, though the total input of SBO in B100 production is trending up. The contribution is down 32.0% from 2021 to 2025. Tallow for biodiesel production could achieve even more significant greenhouse gas emissions reductions compared to plant-based inputs, mainly because they don’t share emissions of upstream activities 4.
In conclusion, although biodiesel production has experienced a decreasing trend due to policy issues in 2025, in 2026, several of the major inputs of biodiesel production are trending upward, reflecting a switching inclusion of different fats and oils inputs. Animal fats and recycled feedstock have seen a strong increasing trend, especially tallow. Other animal fat inputs, such as poultry fat and white grease have seen a decreasing trend. On the other hand, due to the large amount of soybean oil production and the policy restriction on importation of yellow grease, soybean oil may remain the leading oil input for biodiesel production in the future.
4 Xu H, Ou LW, Li Y, Hawkins TR, and Wang M, Life Cycle Greenhouse Gas Emissions of Biodiesel and Renewable Diesel Production in the United States, 2022, Environmental Science and Technology.